What Could Invalidate Your Home Insurance?
12 common mistakes that could put your cover at risk
Home insurance is there to protect your property and belongings when something unexpected happens, whether that is fire, flooding, theft or another insured event.
However, problems can arise if the information on your policy is inaccurate, your circumstances change or important policy conditions are not met.
That does not mean every mistake automatically invalidates your insurance. Depending on the circumstances and the wording of your policy, a claim could be reduced or declined, certain cover could be restricted or, in more serious cases involving misrepresentation, the policy itself could be affected.
Here are 12 common issues worth checking.
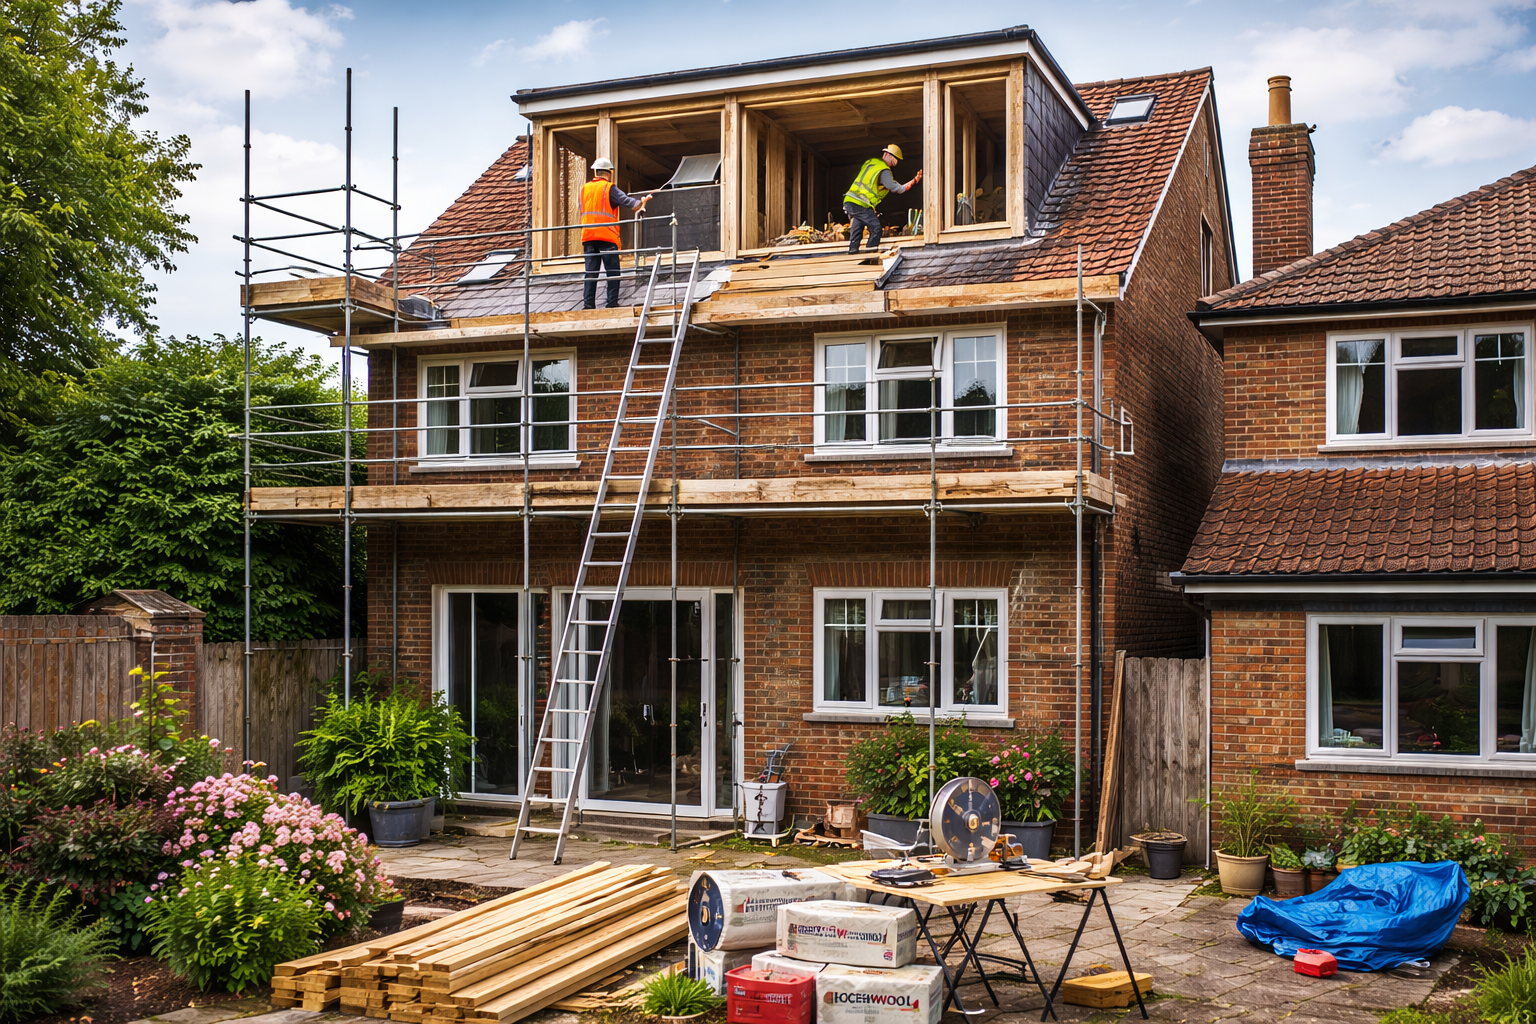
1. Starting building work without checking your insurance
Planning an extension, loft conversion, major renovation or structural alteration?
Before work begins, check whether your insurer needs to know.
Substantial building work can change the risk associated with your property. Parts of the home may be exposed, security arrangements can change and the property may even become temporarily uninhabitable.
Different insurers have different requirements, so it is worth checking before significant work starts rather than assuming your existing cover will continue unchanged.
It is also sensible to check what insurance your builder or contractor has in place.
2. Leaving your home unoccupied for too long
If your property is going to be empty for an extended period, check your policy.
Many home insurance policies restrict certain types of cover once a property has been unoccupied for a specified period, commonly 30 or 60 days, although the exact period and definition of ‘unoccupied’ vary between policies.
This could be relevant if you:
Take an extended holiday
Spend a prolonged period in hospital
Work away from home
Move out during renovation work
Leave the property empty while waiting to sell or move
Certain risks, such as theft, malicious damage or escape of water, may be restricted after the permitted period.
3. Allowing maintenance problems to develop
Home insurance is generally designed to cover insured events rather than routine maintenance or gradual deterioration.
Problems such as:
Long-standing damp
A deteriorating roof
Blocked or damaged guttering
Rotten window frames
Plumbing issues that have been left unresolved
may not be covered in the same way as sudden, unexpected damage.
If you become aware of a maintenance issue, dealing with it promptly can help reduce the risk of further damage and possible problems with a future claim.
4. Running a business from home without checking your cover
Working from home and running a business from your property are not necessarily the same thing from an insurance perspective.
Your risk can change if you:
Store business stock at home
Have customers or clients visiting
Keep specialist equipment at the property
Employ people from home
Run a salon, workshop or other customer-facing business
If the way you use your property changes, check whether your existing home insurance remains suitable and whether separate business cover may be required.
5. Failing to meet security requirements
Your policy may contain requirements relating to locks, alarms or other security measures.
These can be particularly important if the insurer has applied a specific security condition to your policy.
If you have told your insurer that particular locks, alarms or other security devices are fitted, make sure that information remains accurate.
Leaving the property unsecured could potentially affect a theft claim, but it does not automatically mean every claim will be rejected. The circumstances and policy wording will matter.
6. Deliberately damaging the property
Home insurance is designed to cover unexpected losses, not damage intentionally caused by the policyholder.
Policies commonly exclude deliberate or malicious acts by the insured person.
Situations involving deliberate damage by another household member can be more complicated, however, so the exact circumstances and wording of the policy will matter.
7. Providing incorrect or incomplete information
When arranging, renewing or changing your home insurance, it is important to answer the insurer’s questions accurately.
Relevant information could include:
The construction and type of property
Who normally lives there
Previous claims
How the property is used
Whether it is normally occupied
Renovation work where you are asked about it
The value of possessions that need to be declared
If incorrect information comes to light, the outcome will depend on what the error was, whether it was careless or deliberate and what the insurer would have done had it been given the correct information.
Not every mistake automatically invalidates the entire policy.
8. Being underinsured
Having too little cover can create problems when you make a claim.
For buildings insurance, the amount insured may need to reflect the cost of rebuilding your property rather than its market value, depending on how your policy is arranged.
For contents insurance, you should also consider the total replacement value of your belongings.
This can be particularly important for owners of period, unusual or higher-value homes, where rebuilding costs can differ significantly from the property's sale value.
You should also check whether individual valuable items need to be listed separately because they exceed your policy’s single-item limit.
9. Taking in a lodger or renting out your property
Changing who occupies your home can alter the risk being insured.
This could include:
Taking in a lodger
Renting out a room
Letting the entire property
Offering short-term holiday accommodation
A standard home insurance policy may not be designed for every type of letting arrangement.
Check with your insurer or broker before making a change so you know whether your existing cover remains appropriate.
10. Forgetting to review your policy when circumstances change
Homes and households change over time.
You might buy valuable jewellery, artwork or collections, carry out major improvements, set up a home office or change who lives at the property.
Not every change needs to be reported immediately, so check your policy rather than assuming that it does.
However, it is worth reviewing your cover after any significant change to make sure:
Your sums insured remain sufficient
High-value possessions are covered appropriately
Your insurer’s information remains accurate
The way your home is used still fits the policy
11. Delaying a claim or failing to provide information
If something happens, check your policy for instructions on how and when to report it.
Insurers may require incidents to be reported promptly, particularly following theft, major damage or another event where evidence could become harder to obtain over time.
Where relevant, keep supporting information such as:
Photographs or video
Receipts and valuations
Details of damaged or stolen belongings
Contractor reports
Crime reference numbers
A delay does not automatically mean a claim will be rejected, but it can make it harder for the insurer to investigate what happened.
12. Carrying out work that conflicts with policy conditions
Renovations, electrical work, plumbing or other alterations can sometimes cause problems if the work does not meet requirements set out in your policy.
Poor or defective workmanship may itself be excluded, while whether resulting damage is covered will depend on the cause of the loss and the wording of your policy.
For major work, check what your insurer needs to know beforehand and make sure any contractors you use are suitably competent and meet relevant legal or policy-specific requirements.
Simply using a tradesperson without a particular accreditation does not automatically invalidate your home insurance.
Does a mistake automatically invalidate your home insurance?
No.
If incorrect information was provided when the policy was arranged or changed, the outcome will depend on the circumstances.
The insurer may consider what it would have done had it received the correct information, for example whether it would have:
Offered the same policy
Charged a different premium
Applied different terms
Declined to provide cover
A careless mistake may be treated differently from deliberate or reckless misrepresentation.
Other issues may simply mean that a particular type of loss is excluded or restricted rather than the entire policy becoming invalid.
Check your home insurance before you need it
Your home, belongings and circumstances can change considerably over time.
If you have recently carried out renovations, bought valuable possessions, started running a business from home, taken in a lodger or expect your property to be empty for an extended period, it is worth checking your insurance.
You should also review the amount of buildings and contents cover you have from time to time to make sure it remains appropriate.
If you are unsure whether a change needs to be reported, check your policy documentation or speak to your insurer or broker.
It is much easier to clarify your cover now than discover after a fire, flood, theft or other loss that something does not work in the way you expected.
Looking for home insurance?
Peter Best Insurance Services can arrange home insurance for a range of properties and circumstances, including homes with more specialist requirements.
Whatever the type of property you own, making sure your insurer has accurate information and that your cover reflects your current circumstances can help avoid problems later.
Find out more about Peter Best Home Insurance.
Insurance cover, limits, conditions, exclusions and notification requirements vary by insurer and policy. Always check your policy documentation and contact your insurer or broker if you are unsure whether a change needs to be reported.


